The question your ERP can’t answer
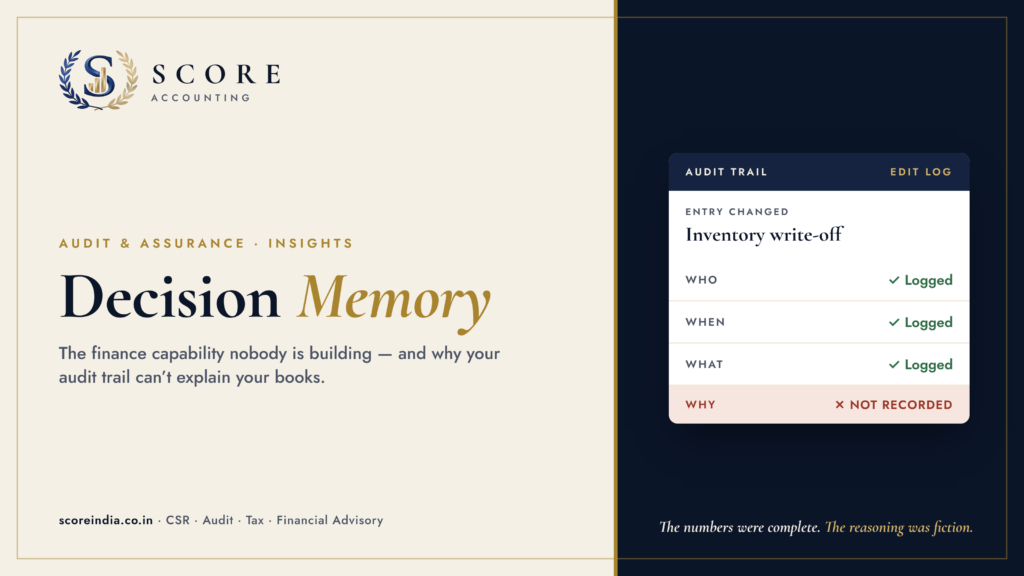
Every finance function today can tell you what happened. Your ERP shows each entry, each amount, and each date. Your audit trail shows who touched it.
Ask why an entry was made that way, and the answer often lives in someone’s head, an email thread, or a WhatsApp message. When that person moves on, the reasoning leaves with them.
That gap creates financial, audit, and governance risk. We call the missing capability decision memory: the habit of recording the reasoning behind a judgement call at the moment it is made.
A retail case: complete numbers, incomplete reasoning
A fashion retail brand with a central warehouse and 30 retail outlets came to us with inventory shrinkage running at 3.5%.
Shrinkage is the difference between inventory recorded in the books and inventory physically verified. It can arise from theft, damage, misrecording, process gaps, or unsupported stock adjustments.
On paper, nothing looked wrong. Every item had an entry and the system balanced. A routine check of the books would have passed.
Our physical verification team went beyond the entries to examine the reasons behind them. The root-cause analysis showed that “damaged returns” were being recorded as “sold” to conceal pilferage. Each entry existed. The reason attached to it was false.
| Measure | Before | After |
|---|---|---|
| Inventory shrinkage | 3.5% | 0.9% |
| Time to result | — | 6 months |
Client name and identifying details have been withheld. The results are based on SCORE’s engagement records for this physical verification assignment.
The lesson for finance leaders is simple: complete records are not the same as truthful records. The ERP could prove what was booked. It could not prove why.
What the audit trail captures—and what it does not
For financial years commencing on or after 1 April 2023, every company that uses accounting software to maintain its books of account must use software with an audit-trail feature. This requirement arises from the proviso to Rule 3(1) of the Companies (Accounts) Rules, 2014.
The software must record an audit trail of every transaction, create an edit log for each change made to the books of account along with the date of the change, and ensure that the audit trail cannot be disabled.
Auditors report on this under Section 143(3) of the Companies Act, 2013, read with Rule 11(g) of the Companies (Audit and Auditors) Rules, 2014. Their reporting covers whether the company used accounting software with an audit-trail facility, whether it operated throughout the year for transactions recorded in the software, whether it was tampered with, and whether it was preserved as required for record retention.
The audit trail forms part of the company’s books of account and should be preserved in accordance with the applicable record-retention requirements, including the minimum eight-year retention period under Section 128(5) of the Companies Act, 2013.
| The audit trail records | The audit trail does not record |
|---|---|
| Who made the change | Why the entry was classified that way |
| When the change was made | What evidence supported the judgement |
| What was changed: created, modified, or deleted | Who agreed with the call, and on what basis |
The audit trail was a meaningful step forward for governance. But it was designed to detect tampering and preserve an edit history—not to explain judgement. A provision, write-off, or reclassification can pass every audit-trail check and still rest on reasoning that nobody can reconstruct.
Where finance reasoning gets lost
In our experience, most finance functions store outcomes, not reasoning. The reasoning leaks out in three places.
- Approvals sit in email threads. Provisions and write-offs are often agreed over email or chat. At audit time, nobody can find the thread, or the thread only says “approved.”
- Judgement lives in people, not systems. The controller who knew why a customer balance was provided for, or why stock was written down, carries that context. When they move on, it goes with them.
- Classifications look clean after the fact. A ledger shows how an entry is classified today. It rarely shows the facts that justified that classification on the day it was booked.
None of this necessarily appears as an error. The books balance and the audit trail remains intact. The risk surfaces later, when an auditor, regulator, buyer in due diligence, or new CFO asks a simple question: why?
Three habits that build decision memory
The next finance capability is not simply more automation. It is decision memory. These are the three habits we encourage every client to adopt.
1. Record the reasoning when you make the call
Do not wait for the auditor or a notice. For every judgement-heavy entry, write two or three lines in the narration or an attached note covering:
- The facts considered
- The basis for the accounting treatment or estimate
- The person who reviewed and approved the judgement
Reasoning written months later is reconstruction, not evidence.
2. Apply maker-checker to judgement calls, not just data entry
Most controls check whether numbers were keyed correctly. Fewer check whether the judgement behind them holds up.
A second person should review the reasoning for provisions, write-offs, reversals, and reclassifications before they are posted. The reviewer should confirm that the facts, supporting evidence, and accounting basis are documented—not merely that the entry has been approved.
3. Run a quarterly “why audit”
Each quarter, select 10 transactions at random, with priority given to judgement-heavy areas such as provisions, write-offs, reversals, reclassifications, stock adjustments, and related-party entries.
The finance team should be able to explain each transaction in under 10 minutes using only what is on record. Any entry that requires a call to the person who booked it is a documentation gap to fix.
The finance controller should maintain a short exception log identifying the transaction, the missing evidence, the corrective action, the owner, and the closure date.
None of these habits requires new software. They require a decision about what your finance team writes down—and when.
A test for your finance team
Pick one judgement-heavy entry from last March: a provision, a write-off, or a stock adjustment.
Could your team defend it today without calling the person who booked it?
If the honest answer is no, you are not alone—and it is fixable. SCORE helps finance teams build decision memory through physical verification and audit and assurance work. We begin with a short “why audit” of your transactions and show you where the reasoning is missing.
Talk to SCORE about a “why audit” for your books at scoreindia.co.in.
Frequently asked questions
What is decision memory in finance?
It is the practice of recording the reasoning behind each judgement call—such as a provision, write-off, or reclassification—at the time it is made. It enables anyone to explain an entry later without relying on the person who booked it.
Is an audit trail mandatory for all companies in India?
No. It is mandatory for every company that uses accounting software to maintain its books of account. For financial years commencing on or after 1 April 2023, such companies must use accounting software with a non-disableable audit-trail feature.
Does the audit trail record the reason for a change?
No. It records the edit log: what changed, when it changed, and who made the change. The reason for the change is not part of the statutory requirement, so companies need to capture it through their own documentation and approval processes.
How long must the audit trail be kept?
The audit trail forms part of the books of account and should be preserved in accordance with the applicable record-retention requirements. Section 128(5) of the Companies Act, 2013 prescribes a minimum retention period of eight financial years.
What is a “why audit”?
It is a quarterly review in which the finance team selects 10 transactions, prioritising judgement-heavy entries, and explains each one in under 10 minutes using only the documentation on record. Entries that cannot be explained reveal where decision memory is missing.
How can SCORE help?
SCORE’s physical verification and audit and assurance teams test whether your records hold up beyond the numbers. Visit scoreindia.co.in to start a conversation.
Sources
- Audit Trail: Requirements & Responsibilities, The Chartered Accountant Journal, ICAI.
- Implementation Guide on Reporting on Audit Trail under Rule 11(g) of the Companies (Audit and Auditors) Rules, 2014, ICAI, Revised 2024 Edition.
- SCORE Physical Verification case study: fashion retail brand with 30 outlets; shrinkage reduced from 3.5% to 0.9% in six months; “damaged returns” root cause.
Disclaimer: This article is for general information only and does not constitute legal, financial or tax advice. Laws, rates and due dates change, and their application depends on your facts. Please consult a qualified professional before acting on it.